Auditor-General Raises Alarm Over N3.62bn Irregularities at Power Training Institute

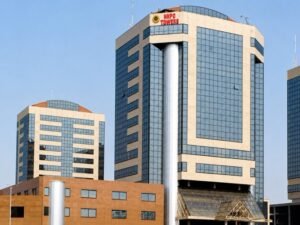
The Office of the Auditor-General for the Federation has identified financial irregularities amounting to about N3.62 billion at the National Power Training Institute of Nigeria (NAPTIN).
The findings are contained in the Auditor-General’s 2024 Annual Report on Non-Compliance and relate to activities carried out between January 2022 and December 2023.
A major portion of the questioned amount, about N2.77 billion, involved proceeds from the sale of bidding documents and tender fees which, according to the audit report, were not remitted to the Consolidated Revenue Fund as required by government regulations.
The auditors also said the institute failed to provide adequate documentation to support some of the transactions, including records relating to bid purchases made through Remita.
Another major issue involved N547.21 million reportedly spent on various store items across 11 transactions. The auditors said there was no evidence of delivery or Store Receipt Vouchers confirming that the items had been received and recorded.
The audit further questioned approximately N196.59 million spent on three constituency projects involving electricity transformers and solar streetlights in Ogun, Lagos and Osun states.
According to the report, the institute did not provide sufficient evidence that the contractors met the required procurement conditions. The auditors also noted the absence of documentation showing that the projects were properly monitored and certified by the relevant federal ministry.
Other issues highlighted in the report included N29.65 million in duty tour allowances, sitting allowances and honoraria charged to a constituency project account.
The auditors also found that the institute under-remitted about N4.12 million in Value Added Tax (VAT) from 21 contracts valued at N136.86 million.
Additional questioned expenditures included administrative charges, provisions for electricity certification and commissioning, contingency payments and funds transferred for a youth and women training programme for which supporting evidence was reportedly unavailable.
The Auditor-General also criticised the institute for failing to provide several important financial documents for examination, including its trial balance, general ledger and records of remittance inflows and outflows.
The report said the absence of the documents restricted the auditors’ ability to properly verify the transactions and assess the institute’s financial accountability.
The Auditor-General recommended that the institute’s Director-General explain the questioned expenditures before the National Assembly’s Public Accounts Committees. It also called for the recovery and remittance of funds where appropriate, with possible sanctions under applicable financial regulations.
The report further pointed to weaknesses in the institute’s internal control systems, warning that such gaps could expose public funds to revenue leakages and unsupported payments.
About The Author